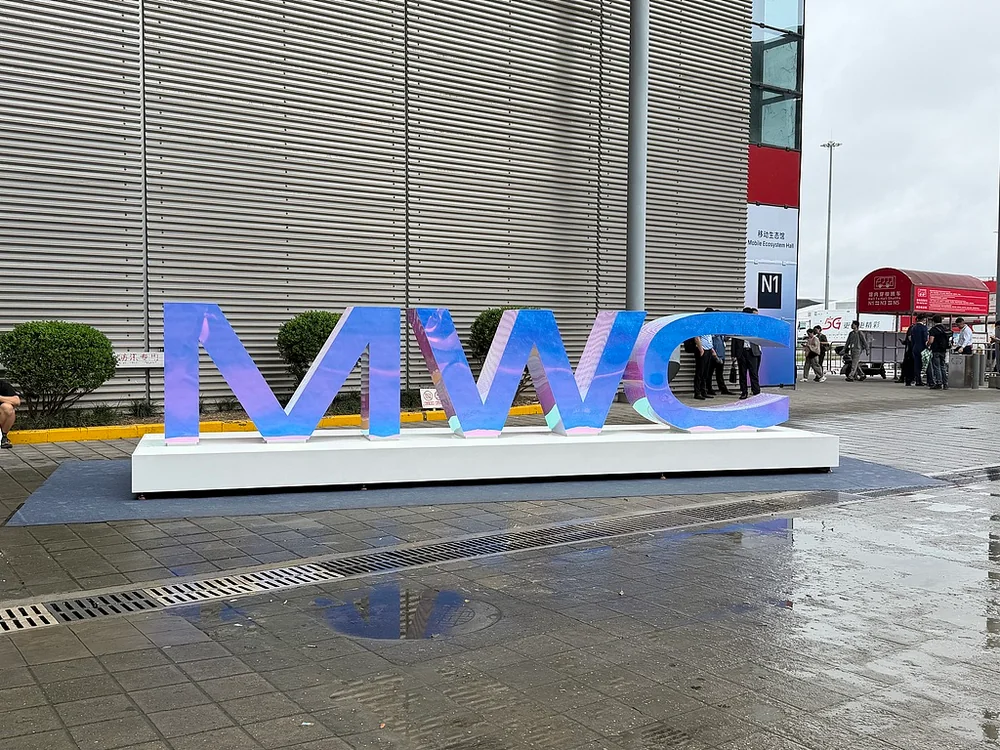
Blue Whale News, June 27 (Reporter Zhai Zhichao) - The 2026 MWC Shanghai opened on schedule recently. Unlike last year's atmosphere of intensive 5G-A commercial order placements, this year's exhibition halls exude a cautious, pragmatic feel: the first-ever independent '6G Industry Ecosystem Area' and the 'Future Constellation' satellite zone, though bustling with visitors, have industry players more focused on when technology can turn into real returns.
Blue Whale tech reporters found that in the 6G direction, three paths—integrated sensing and communication, AI-native, and space-air-ground integration—are now uncontroversial, with chip makers even starting early R&D stocking. In the satellite internet field, the 'land grab' for orbital frequencies has essentially ended, with scale networking and cost reduction becoming the new themes. However, consensus stops at the technical level: terminal makers and investors are mostly waiting, with the former waiting for killer apps and the latter unable to calculate return cycles. Even international satellite players that have achieved profitability are struggling with early cultivation of the consumer market.
As the financial accounts of 5G investment are not yet fully settled, 6G and satellite internet are collectively entering a transitional phase of 'clear vision but hard to deliver.' Technical routes are narrowing, while commercial exits look increasingly broad. Under real investment return constraints, the industry needs a more practical answer than 'grand narratives.'
6G Technology Paths Converge, Commercial Closure Still Being Explored
Walking into the 6G industry ecosystem exhibition area in Hall N3 of MWC Shanghai, five sections—the Beijing 6G Lab General Area, Communication Enhancement, Integrated Sensing and Communication, Integrated Communication Computing Intelligence, and Space-Terrestrial Integration—break down 6G's core technical vision clearly. On-site staff told Blue Whale tech reporters that this is the first time MWC Shanghai has dedicated a hall to 6G, sending a clear signal: 6G has moved from concept discussion to the key stage of system verification.
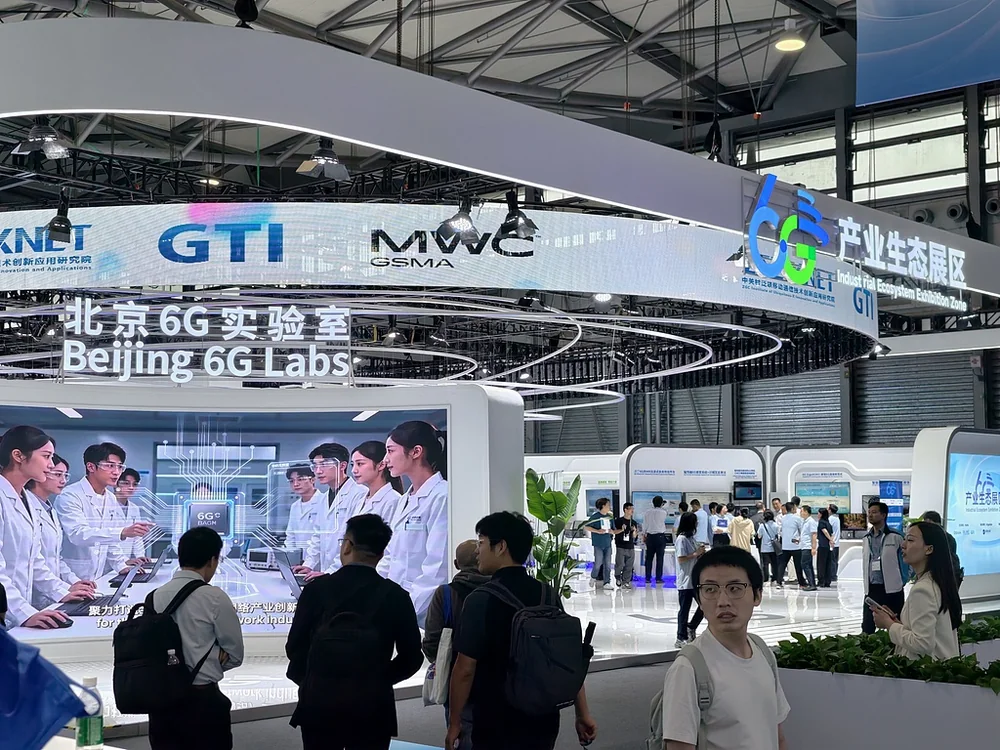
'If last year people were still debating what 6G should do, this year the debate is about how to do it and what trade-offs to make,' said a technician from the Beijing 6G Lab General Area. Currently, the three enhancement paths—integrated sensing and communication, AI-native, and space-air-ground integration—have formed basic industry consensus, while key technologies like terahertz communication and intelligent reflecting surfaces have entered prototype verification.
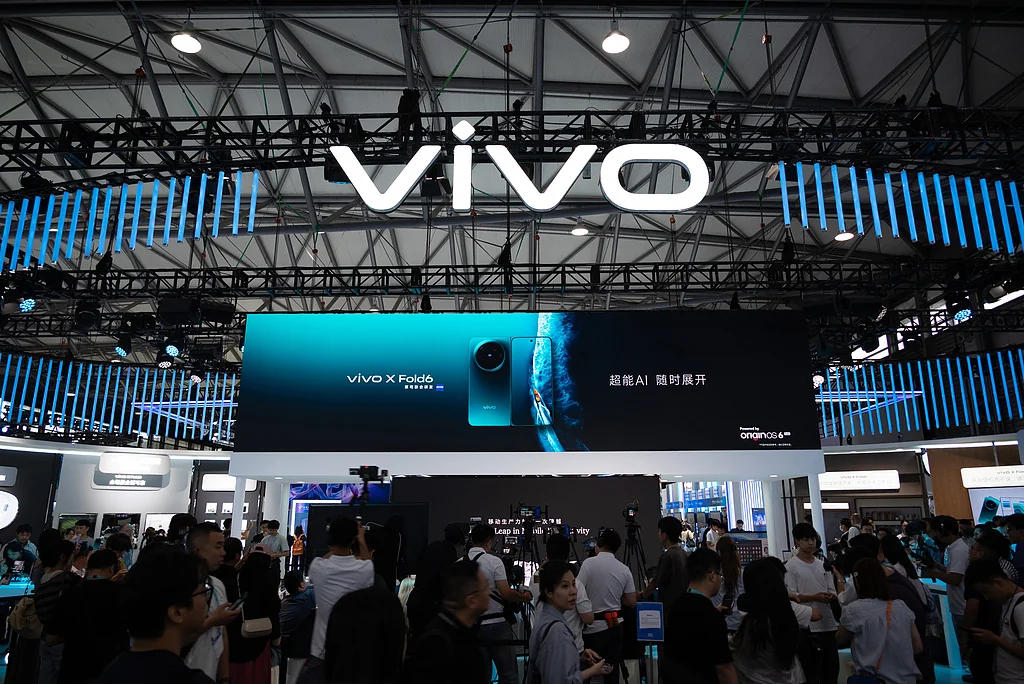
The pace of upstream industry chain layout is clearly accelerating. At this exhibition, Qualcomm demonstrated an end-to-end 6G prototype system; GalaxySpace publicly showcased its self-developed second-generation phased array antenna for direct phone-to-satellite connectivity in the 6G ecosystem area; vivo exhibited its 6G pre-research prototype and technology roadmap. It is understood that compared to Xiaomi, which focuses on underlying transmission algorithms, and OPPO, which focuses on communication paradigm innovation, vivo's display direction leans more toward end-to-end systems and application landing, with its complete 6G test system covering MR terminals, 6G terminal prototypes (UE), 6G base stations (RAN), and core network.
A domestic chipmaker's on-site representative told reporters that the company's internal 6G pre-research team has doubled in size compared to last year, explaining: 'Waiting until the standard freezes would be too late; we must have technical reserves ready in advance.'
However, compared to the enthusiasm upstream, terminal makers are relatively cautious. Blue Whale tech reporters asked several mobile phone brands about their 6G terminal plans in the 6G area, with responses mostly being 'closely monitoring,' and few consumer-grade product demonstrations for 6G. A 6G pre-research director from one of the world's top five mobile phone vendors said in informal conversation that it is still difficult to produce a clear 6G phone commercial roadmap. The core reason is not lack of technical capability, but that the terminal side is still evaluating the conversion path from user needs to application scenarios. In his view, the experience dividend of 5G has not yet been fully released, and 6G's envisioned scenarios like immersive holographics and multi-dimensional senses are still some distance from the mass consumer market.
The investment community is similarly cautious. A TMT-focused early-stage investor met by Blue Whale tech reporters at the exhibition said that while the technology direction is impressive, from an investment perspective, 5G's capital returns are still being absorbed, and 6G's R&D and network deployment costs are enormous, with exit cycles and return expectations currently lacking sufficient data support. He admitted that for now, it's more about keeping track and waiting for clearer commercial signals before deciding to act.
'Future Constellation': Landscape Settling, Profit Path Yet to Be Verified
Unlike the 6G area, which focuses on key technology verification, the newly established 'Future Constellation' satellite industry zone presents a different industrial rhythm—the orbital landscape is taking shape, and participants are entering a phase of intensive resource and cost management.
Domestic LEO broadband and narrowband constellation operators such as SpaceTime DaoYu, GuoDian HighTech, and YuanXin Satellite, along with international players like Iridium, all set up sizable booths. SpaceTime DaoYu displayed real LEO satellite internet terminals for scenarios like ocean-going vessels and desert mining areas; GuoDian HighTech focused on showcasing the Tianqi constellation's IoT application cases; YuanXin Satellite staff even made a live call, playing a video call test screen achieved via the 'Qianfan Constellation.'
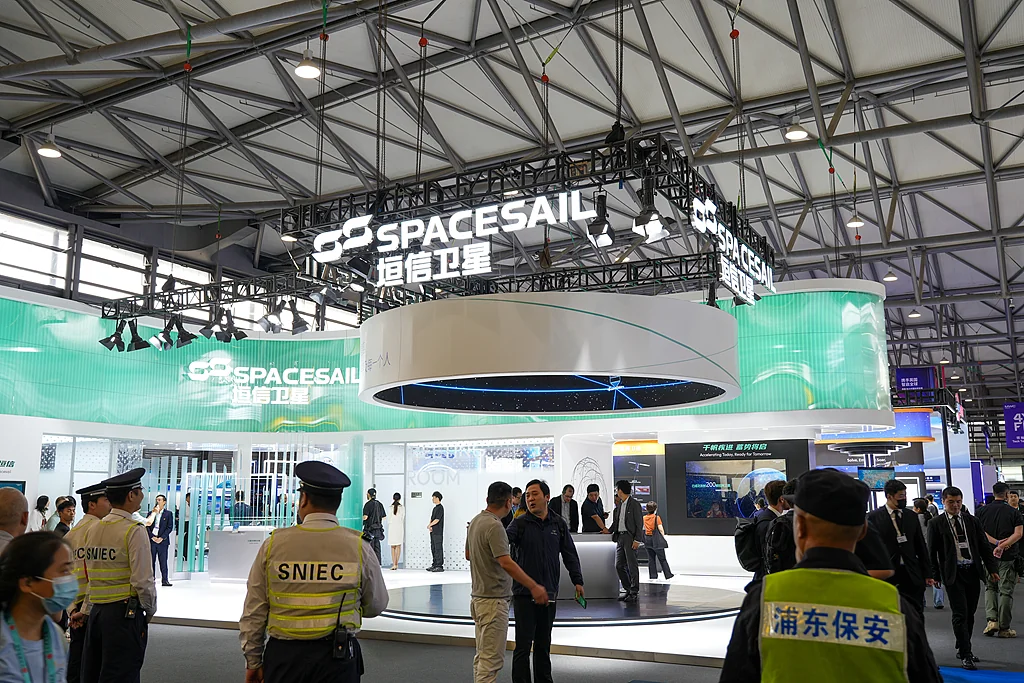
'The battle for orbital and frequency resources has basically ended; the current key lies in scale deployment and cost control,' said a GuoDian HighTech on-site representative. He revealed that the company's mass production cost for narrowband communication payloads is continuously declining, but also pointed out that the user scale for satellite internet services has not yet reached the breakeven point, at least for the next few years, with government and industry orders still supporting the revenue base.
In the process of forming a profit model, terminal cost is a notable link. Blue Whale tech reporters discussed satellite communication terminal material costs with antenna and module makers, who generally said costs are falling rapidly and are ready for integration into mainstream device designs, but most declined to disclose specific figures.
A business manager at the Iridium booth told reporters that Iridium has achieved positive cash flow through narrowband voice and low-speed data services, but the traditional market space is nearing saturation, requiring expansion into IoT and emergency communications for next-step growth. Meanwhile, domestic LEO broadband constellation operators are still in a catch-up phase prioritizing scale, and achieving breakeven will require time and user accumulation.